 Halin
Mixed Income Earner Tax in the Philippines (2026): Salary + Side Hustle Guide
November 5, 2026 · 8 min read · Halin AI Team
You have a day job — and a side hustle. Maybe you freelance at night, sell online on weekends, or take consulting gigs. In BIR terms, that makes you a mixed-income earner: someone with both compensation income (salary) and business or professional income. Your employer handles the tax on your salary. The side income is on you — and the rules are different from both "employee" and "pure freelancer."
Am I a mixed-income earner?
Yes, if during the year you earn both:
- Compensation income — salary, wages, or allowances from an employer, with a Form 2316 at year-end; and
- Business or professional income — freelancing, consulting, online selling, a sari-sari store, rentals run as a business, and similar.
It doesn't matter how small the side income is, or whether your clients are local or abroad. If it's regular income from a trade or profession, it's taxable — and you're expected to register it.
Step 1: Register your side income — with the same TIN
You already have a TIN from your employer. Do not get a second one. Having more than one TIN is prohibited and penalized. Instead, you update your existing registration to add your business or profession:
- Register as a mixed-income earner — through the BIR's online registration system (ORUS) or at your RDO (BIR Form 1901 is the registration form for self-employed and mixed-income individuals).
- You'll get a Certificate of Registration (Form 2303) listing your tax types and filing obligations.
- You'll also need books of accounts and registered invoices for your side business.
Our BIR registration guide walks through the process in more detail.
Step 2: Choose how your side income is taxed
Your salary is always taxed at graduated rates — that part isn't optional, and your employer withholds it. For your business income, you choose between two options:
Option A: 8% on gross business income
- 8% of your gross sales or receipts from the side business — no expenses deducted.
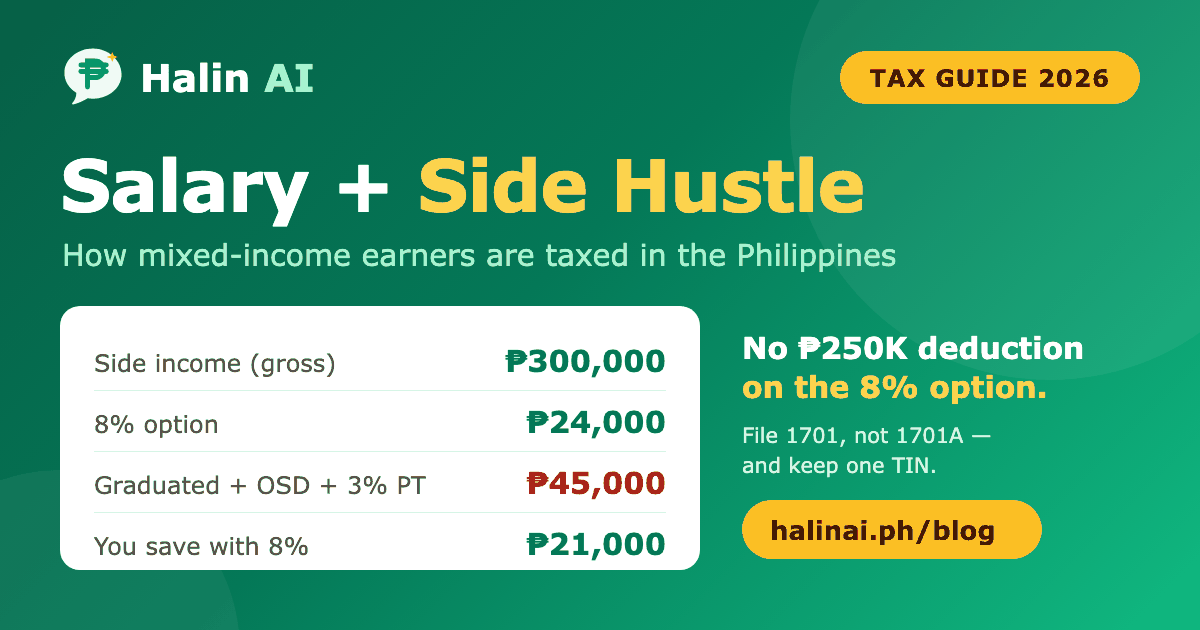
- The key difference for mixed-income earners: there's no ₱250,000 deduction. Pure freelancers on 8% only pay on gross above ₱250,000. Mixed-income earners pay 8% from the first peso, because the ₱250,000 zero-tax bracket is already applied to your salary.
- It replaces the 3% percentage tax — no 2551Q to file.
- Available only if your gross business income is ₱3 million or less and you're not VAT-registered. You elect it on your first quarterly return of the year (or at registration); otherwise you default to graduated rates.
Option B: Graduated rates
- Your net business income (gross minus expenses — either itemized or the 40% OSD) is added to your taxable salary, and the total is taxed using the graduated table.
- Because your salary already fills the lower brackets, your side income is taxed at your highest bracket.
- If you're non-VAT, you also pay 3% percentage tax on gross business income (2551Q).
A worked example
Ana earns a ₱400,000 taxable salary and makes ₱300,000 in gross freelance income on the side, with few expenses.
Tax on her salary (withheld by her employer either way): ₱22,500.
Option A — 8%: ₱300,000 × 8% = ₱24,000 on the side income. No percentage tax.
Option B — graduated with OSD:
- Net business income: ₱300,000 − 40% OSD = ₱180,000
- Total taxable income: ₱400,000 + ₱180,000 = ₱580,000 → tax ₱58,500
- Extra income tax from the side income: ₱58,500 − ₱22,500 = ₱36,000
- Plus 3% percentage tax: ₱9,000
- Total on the side income: ₱45,000
In this case, 8% saves Ana ₱21,000 — even without the ₱250,000 deduction. That's typical when expenses are low and the salary already sits in the 15–20% bracket. Graduated rates can win when your business expenses are high (itemized) or your salary is small. Compare both for your own numbers before your first quarterly filing — see 8% vs graduated rates.
Step 3: What to file, and when
- 1701Q every quarter — for your business income only (your salary isn't included). Due May 15, Aug 15, and Nov 15. See how to file 1701Q.
- 2551Q every quarter — only if you're on graduated rates and non-VAT.
- Annual ITR: BIR Form 1701 — due April 15. Mixed-income earners file 1701, not 1701A (1701A is for people with purely business or professional income). Your salary, business income, and taxes already paid all come together here.
- Attach your Form 2316 from your employer. The tax withheld from your salary is credited against your total tax due. Freelance withholding on Form 2307s is credited too.
All dates are in the 2026 BIR tax calendar, and you can pay online via GCash or Maya.
Mistakes that cost mixed-income earners the most
- Assuming "my employer already filed for me." Substituted filing — where your 2316 counts as your return — only applies to people with purely compensation income from one employer. Once you have side income, you file your own 1701.
- Getting a second TIN for the side business. Update your existing registration instead.
- Claiming the ₱250,000 deduction on the 8% option. It doesn't apply to mixed-income earners — and the underpayment shows up later with interest.
- Not filing quarterly because "it's just a side hustle." Missed 1701Qs become open cases with penalties, even in quarters with zero side income.
- Not keeping records. If you're on graduated rates with itemized deductions, you need receipts and books to back up every expense.
Keep your side income separate and organized
The hardest part of being a mixed-income earner isn't the tax table — it's keeping your side-hustle income and expenses straight on top of a full-time job. Halin AI makes that a few seconds a day: chat your sales and expenses as they happen (in English, Tagalog, or Bisaya), snap receipts, and see your quarterly gross, your estimated tax under 8% vs graduated, and a pre-filled 1701Q worksheet — with reminders before every deadline. 100% free during early access — start here.
Common questions
Can a mixed-income earner use the 8% option?
Yes — but only on business income, and without the ₱250,000 deduction. Your salary is still taxed at graduated rates.
Do I file 1701 or 1701A?
1701. 1701A is only for individuals earning purely from business or profession.
Is my salary included in 1701Q?
No. Quarterly returns cover business income only. Your salary and business income are combined in the annual 1701.
Do I need a new TIN for my side business?
No — and you shouldn't get one. Use your existing TIN and update your registration to add your business or profession.
What if my side income stops?
Keep filing until you formally update or close your business registration. Otherwise, the quarterly obligations — and penalties for missing them — continue.
Disclaimer: General information only, not tax or legal advice. Rates, forms, and rules change and depend on your situation — verify at bir.gov.ph or with your RDO, and have a CPA review your filings.
Gusto mo ng bookkeeper na kasing-dali ng chat?
I-chat mo lang ang benta mo — Bisaya, Tagalog, o English — at si Halin na ang bahala sa libro, tax computation, at BIR reminders. Libre habang early access!
Simulan — libre 🚀Basahin din:
- Bisaya Business Words in English: 30 Terms Every Negosyante Should Know
- How to Pay BIR Taxes Online (2026): GCash, Maya, LandBank & More
- BIR Form 2307 Explained: The Tax You Already Paid (and How to Claim It)
- Halin Meaning in English: The Bisaya Word for Sales (Not Profit)
- Your Year-End Tax Checklist: What to Do Before December 31 (Philippines, 2026)
- Haven't Been Filing? Understanding BIR Open Cases and How People Catch Up (2026)
- Crossing ₱3 Million: What Happens When Your Business Outgrows Non-VAT Status (2026)
- What Business Expenses Can You Actually Deduct? A Philippine Freelancer Guide (2026)
- Invoice vs Official Receipt: What Filipino Freelancers and Small Businesses Must Issue Now (2026)
- No Payslip? How Freelancers and Small Business Owners Can Prove Income in the Philippines
- OSD: The 40% Tax Deduction Most Filipino Freelancers Have Never Heard Of (2026)
- BIR Books of Accounts (2026): Samples, Types & How to Keep Them
- Is Your Business Actually Making Money? How to Know (Without an Accountant)
- How to File BIR Form 1701Q for Q3 2026 (Due Nov 15): Step-by-Step Guide
- Freelance Tax in the Philippines (2026): How Much Do You Actually Pay?
- Paano Mag-simula ng TikTok Shop sa Pilipinas (2026): Setup, Requirements, at Buwis ng Online Sellers
- BIR Tax Deadlines 2026: Kumpletong Calendar para sa Freelancers at Small Business Owners
- Bookkeeping for Freelancers and Small Businesses in the Philippines: The Simple 2026 Guide
- Paano Mag-file ng BIR Form 2551Q: Step-by-Step Guide para sa Freelancers at Small Business (2026)
- 8% Flat Tax vs Graduated Rates: Alin ang Mas Sulit para sa Freelancers? (2026)
- Paano Mag-register sa BIR bilang Freelancer o Online Seller: Complete Guide (2026)